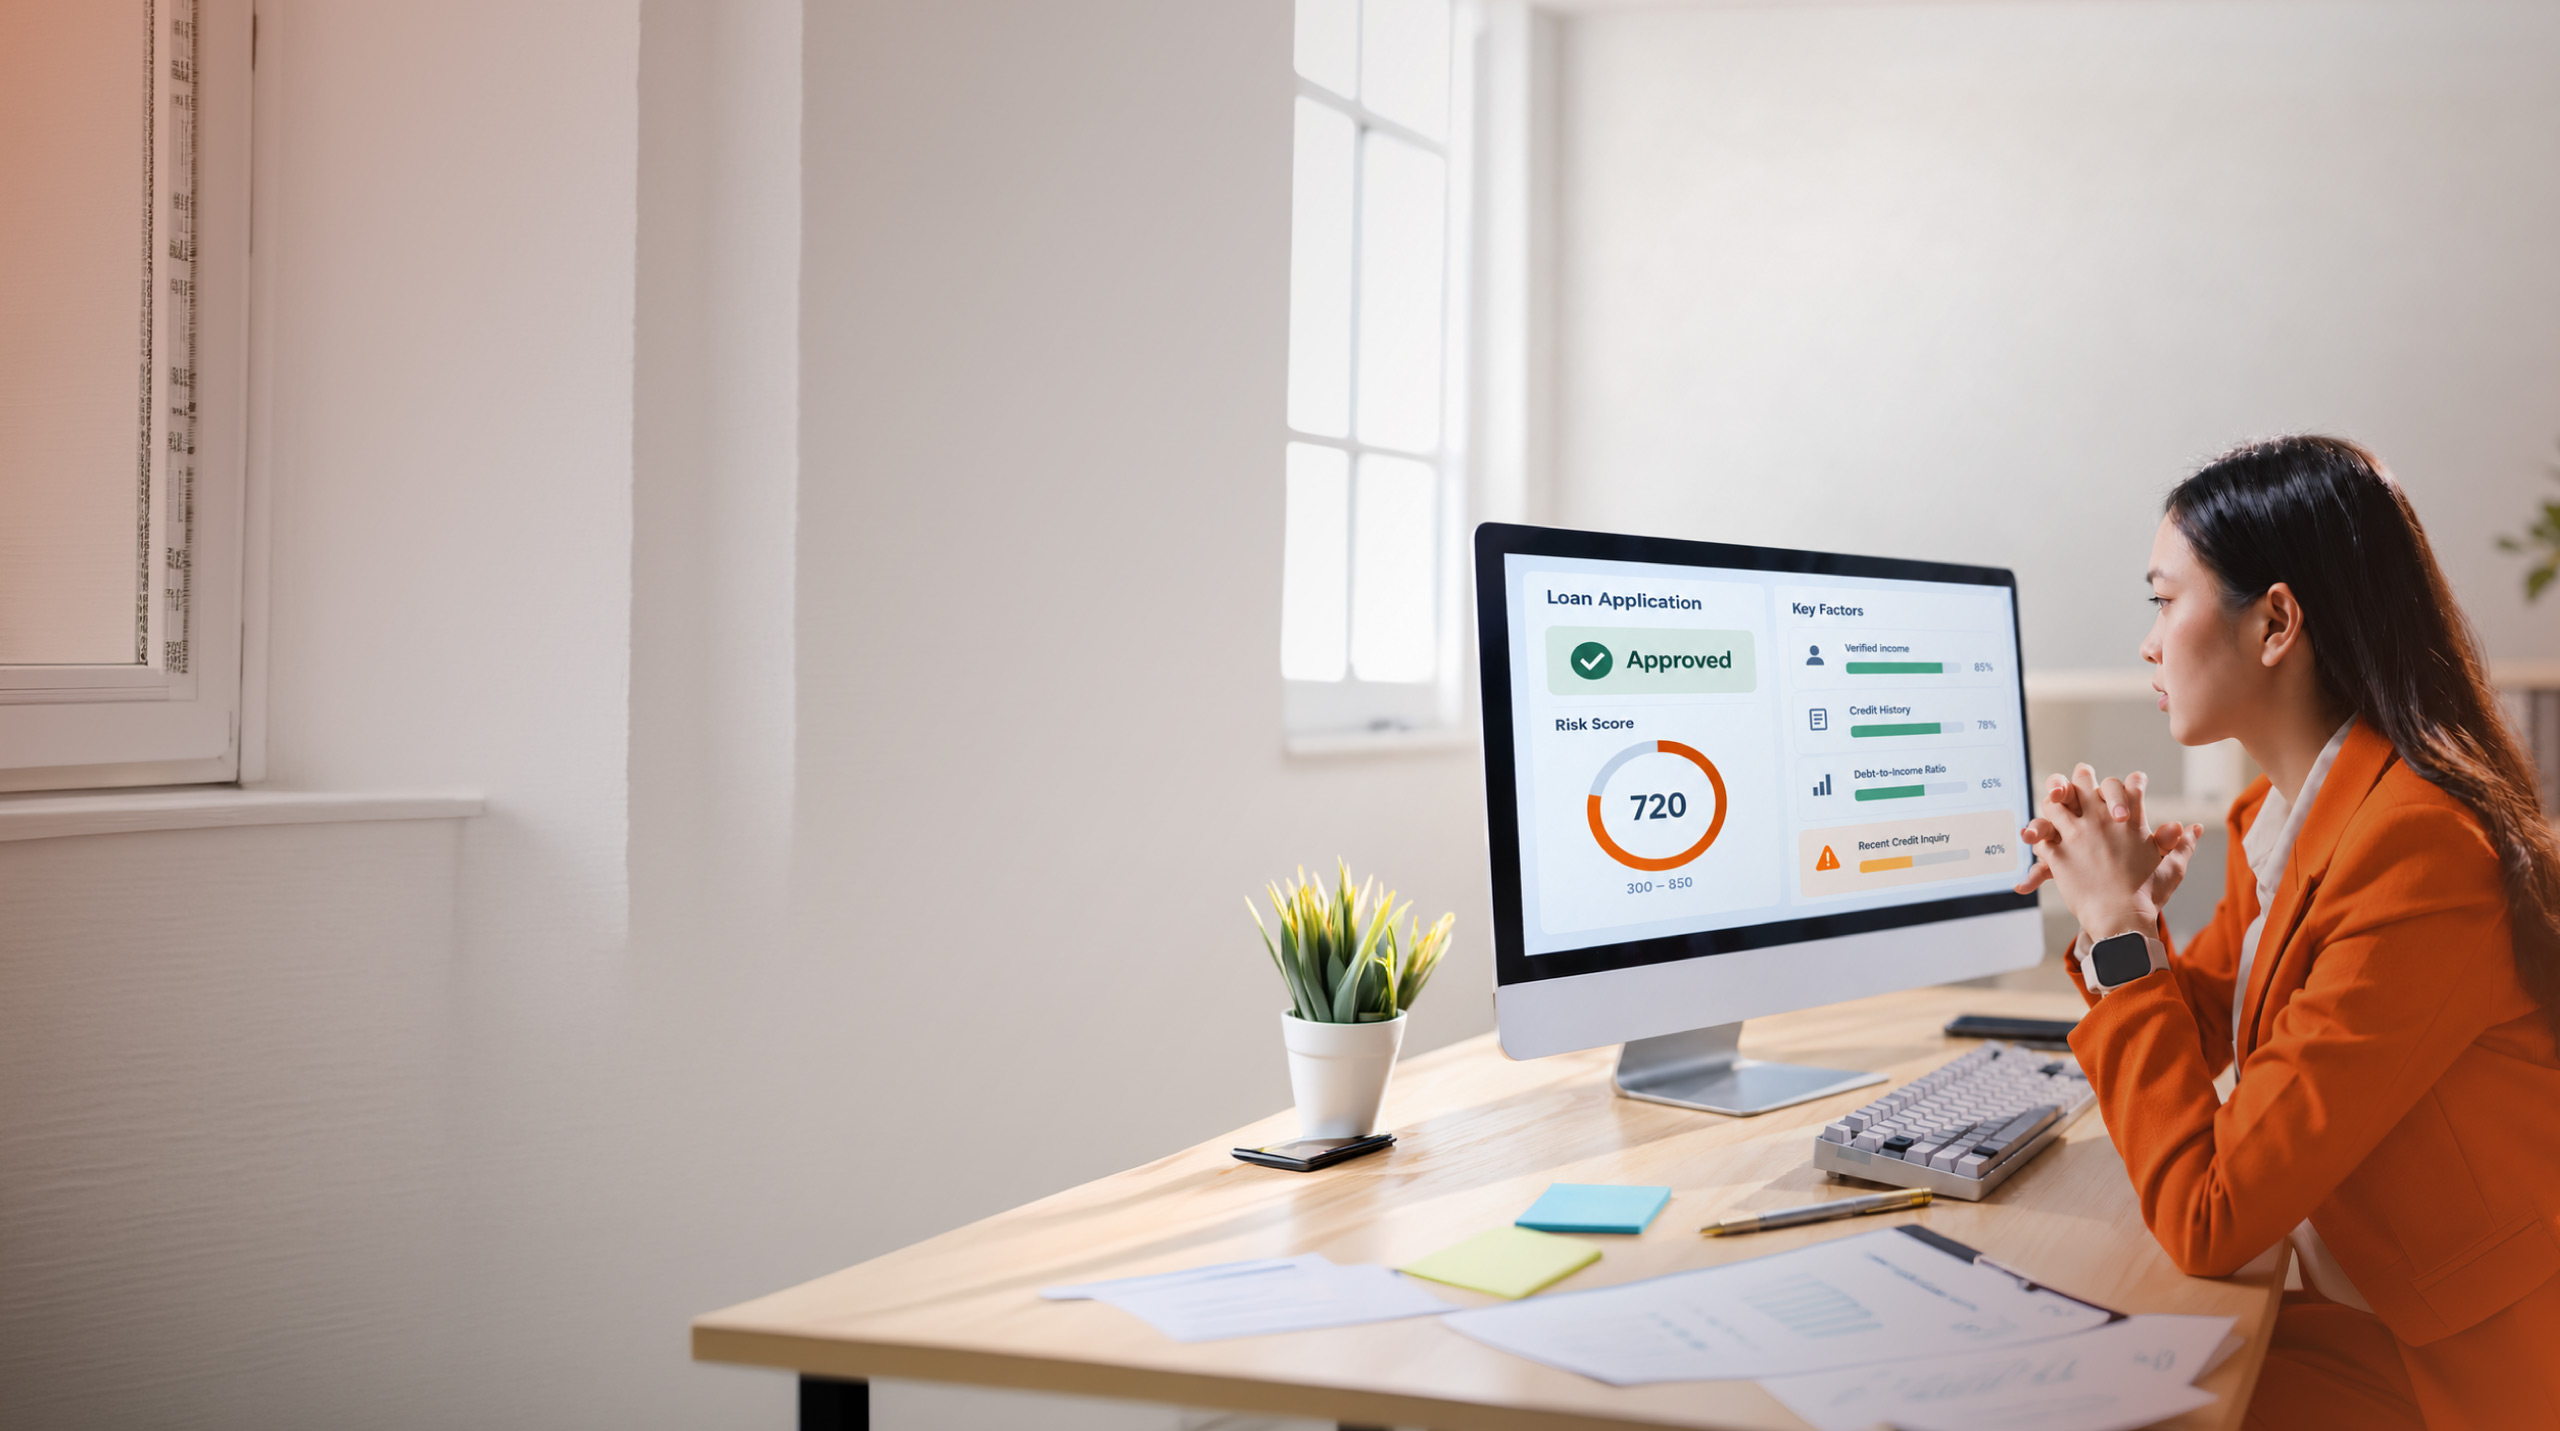
Why Agentic AI Is Reshaping the Future of Commercial and SMB Lending
For decades, competitive advantage in lending was built on relationships, risk expertise and scale. While those fundamentals remain critical, today’s lending environment is placing unprecedented pressure on financial institutions to do more with less.
Borrowers expect near-instant responses. Regulators demand greater transparency and auditability. Operating costs continue to rise. At the same time, lenders are expected to grow portfolios without proportionally increasing headcount.
Yet many institutions still rely on workflows designed for a different era. Critical activities such as borrower onboarding, document collection, financial spreading, credit memo preparation and portfolio monitoring remain heavily manual, creating delays, operational bottlenecks and inconsistent experiences.
The question facing lending leaders is no longer whether AI can help. It is how quickly they can leverage it to transform their lending operations.
The Hidden Cost of Manual Lending Processes
Most lenders recognize that manual processes are inefficient. Less visible is the cumulative impact those inefficiencies create across the credit lifecycle.
Lengthy borrower onboarding processes delay application readiness. Analysts spend valuable time gathering and validating information instead of evaluating risk. Credit teams manually prepare memos and financial spreads. Portfolio reviews occur periodically rather than continuously, allowing emerging risks to develop before they are detected.
Industry estimates suggest that 65% to 80% of underwriting effort is often spent gathering, validating and analyzing borrower information instead of making lending decisions.
When credit professionals spend most of their time on administrative tasks, institutions limit their own growth.
Why Lending Leaders Are Prioritizing Agentic AI
The lending industry is reaching an inflection point. Four market forces are accelerating the adoption of AI-powered lending operations.
First, rising operating costs make people-intensive processes unsustainable. Second, regulatory scrutiny requires demonstrable explainability and traceability in credit decisions. Third, borrowers compare lenders on responsiveness and delays hand business to competitors. Finally, growth expectations continue to outpace staffing capacity.
These challenges cannot be solved through incremental process improvements alone. They require a fundamentally different operating model.
Moving Beyond Automation to Intelligent Orchestration
Traditional automation focuses on individual tasks. Agentic AI takes a broader view.
This also changes the role of the automation lenders already own. Business process management platforms and robotic process automation removed keystrokes and digitized routing and those investments still hold value. What they cannot do is interpret an unstructured tax return, reconcile conflicting financials or decide what happens next.
Agentic AI complements that installed base by operating above it: deterministic bots keep executing rules-based steps, while agents absorb the judgment-intensive, exception-heavy work that previously broke scripted workflows and fell back to people. Where those workflows are brittle and unable to adapt to changing document formats or credit policies, agents will steadily displace them. In commercial lending operations, the effect is fewer stalled files, smaller exception queues and automation that no longer breaks when a borrower package deviates from the template.
Rather than optimizing isolated steps, AI agents can work together across the lending lifecycle, moving applications from submission through analysis, risk assessment, compliance validation and decision support. Throughout the process, human experts remain in control of final lending decisions.
This shift from task automation to orchestration accelerates decisions while preserving the governance responsible lending requires.
The result is not replacing underwriters but empowering them to focus on evaluating opportunities, exercising judgment and managing risk.
Reimagining the Credit Lifecycle with AI
Turning Borrower Onboarding into a Competitive Differentiator
AI-powered intake capabilities can automate document collection, validate borrower submissions and prepare complete underwriting-ready packages before analysts begin their review.
The impact is significant: underwriting readiness can move from weeks to days, improving both operational efficiency and borrower satisfaction.
Transforming Credit Memos into Decision Support Assets
Credit memo preparation is one of the most time-consuming activities in commercial lending.
AI can automatically assemble information from borrower documents, financial spreads and supporting materials to generate institution-specific credit narratives with full traceability to underlying sources.
Instead of spending hours documenting information, analysts can focus on interpreting insights and making stronger credit decisions.
Accelerating Financial Analysis
Financial spreading remains a critical yet labor-intensive part of underwriting.
Modern AI solutions can extract financial data, map it to institution-specific structures and generate underwriting-ready spreads aligned with internal standards.
This approach enables analysts to review and refine financial analyses rather than manually reconstruct them. Organizations have reported up to 36% faster financial spreading, creating meaningful productivity gains across credit operations.
Shifting from Periodic Reviews to Continuous Credit Monitoring
Risk management has traditionally been retrospective.
AI-powered monitoring enables ongoing portfolio surveillance, continuously assessing borrower performance and identifying potential issues before they become significant credit events.
By surfacing risks earlier, institutions can act proactively and improve overall credit quality.
Scaling SMB and SBA Lending Efficiently
High-volume lending businesses often face an efficiency challenge: maintaining speed without compromising consistency.
AI-driven origination can automate document analysis, cash flow assessment and credit evaluation, helping lenders process more applications while maintaining governance standards.
For SBA lending, automated intake and validation can increase capacity without proportional staffing increases.
Responsible AI Must Be Built into Lending
Speed alone is not enough.
AI-driven processes must remain transparent, auditable and compliant with regulatory expectations.
That means explainable recommendations, end-to-end audit trails and human-in-the-loop validation to maintain accountability and trust across the credit lifecycle.
Organizations that balance innovation with governance will unlock sustainable value from AI.
The Future of Lending Is Scalable, Intelligent and Human-Guided
The most successful lenders will not simply process applications faster. They will operate fundamentally differently.
Combining lending expertise with agentic AI accelerates decisions, improves efficiency, strengthens risk visibility and elevates borrower experience.
The opportunity is clear: scale lending growth without scaling operations.
For lending leaders navigating increasing competition, higher expectations and growing complexity, the path forward is not more manual effort. It is intelligent orchestration that enables people and AI to work together more effectively.
The institutions that embrace this shift today will define the lending experience of tomorrow.
Author Profile
Rajesh Stephen
Associate Vice President, Domain Consulting at Persistent Systems